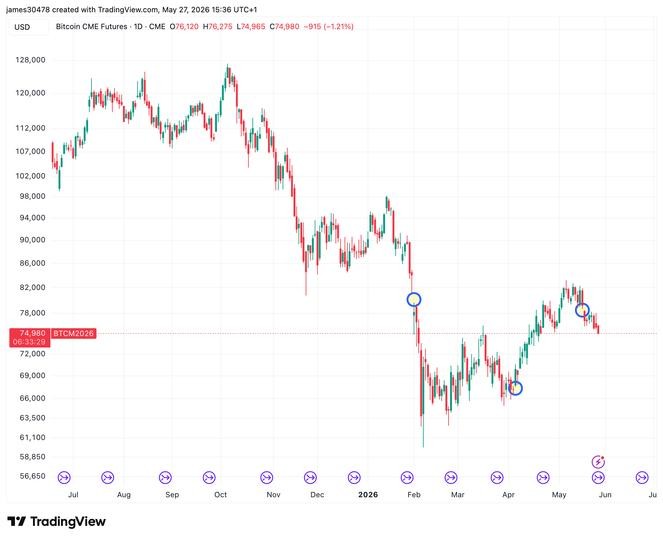
Volatility would often spike sharply at the 11PM UTC Sunday reopen as futures markets recalibrated to wherever spot had drifted over the weekend. That weekend price action was characteristically low-volume and largely noise, thin order books amplifying moves that would frequently snap back once institutional participants logged on late Sunday.
With CME's maintenance window now scheduled for that same 10PM–11PM UTC Sunday slot, it's worth noting that window may retain some of its old character. Liquidity will thin as Globex goes offline, and the reopen at 11PM could still see brief volatility bursts as the market finds its footing. It's a dynamic worth monitoring closely in the weeks ahead.
That era is now largely over. By aligning futures trading with bitcoin's native 24/7 market structure, CME is reducing weekend risk premia and improving hedging efficiency for institutional participants. Asset managers, hedge funds, and corporate treasury desks can now manage exposure continuously rather than waiting for markets to reopen.
Still, CME remains behind where liquidity truly sits. Founder & CEO, Cole Kennelly at Volmex Labs, told CoinDesk, BlackRock's IBIT ETF options currently holds roughly $27 billion to $30 billion in open interest, dwarfing CME Bitcoin futures options, which sit closer to $800 million to $900 million. That imbalance helps explain why the BVIV-US Index (BVUS), derived from IBIT's deeper options market, has emerged as the preferred institutional benchmark for Bitcoin volatility.
Offshore perpetual futures and ETF options will likely retain their dominance for now. But CME's shift to 24/7 trading removes a critical friction point.
As it stands, there are currently three open CME gaps, all created this year. Two sit above Bitcoin’s current spot price of roughly $73,000, one formed in late January near $80,000 and another around $78,500. The third remains open below the market, just under $70,000.

 coindesk.com