Meanwhile, the Aug. 19 quarterly filing put the production number in sharper relief. Olenox had $3.40 million of total current assets at June 30, leaving a working-capital deficit of about $22.9 million.
Importantly, its current liabilities were not all debt immediately due. They included $14.55 million of accounts payable and accrued expenses. Other items included lease current maturities, amounts due to affiliates, credit lines, derivative liabilities, convertible notes, short-term notes and current maturities of long-term debt.
Olenox nevertheless said its losses, negative working capital and negative operating cash flows raised substantial doubt about its ability to continue as a going concern. It had no committed sources of additional financing at June 30. The company said it might have to delay or curtail planned activities if it could not obtain capital when needed.
Seller notes add fixed obligations
Separately, the mining acquisition added a separate fixed obligation. Olenox paid preliminary upfront consideration of $30 million for CS Digital. That included $14 million of Series E preferred stock and $16 million of unsecured promissory notes, plus warrants and potential contingent stock consideration.
Under the deal, the seven seller notes carry 10% annual interest, mature in May 2029 and require interest-only payments beginning in August 2026. The stated principal and rate imply $1.6 million of simple annual interest. The note form provides for quarterly payment mechanics.
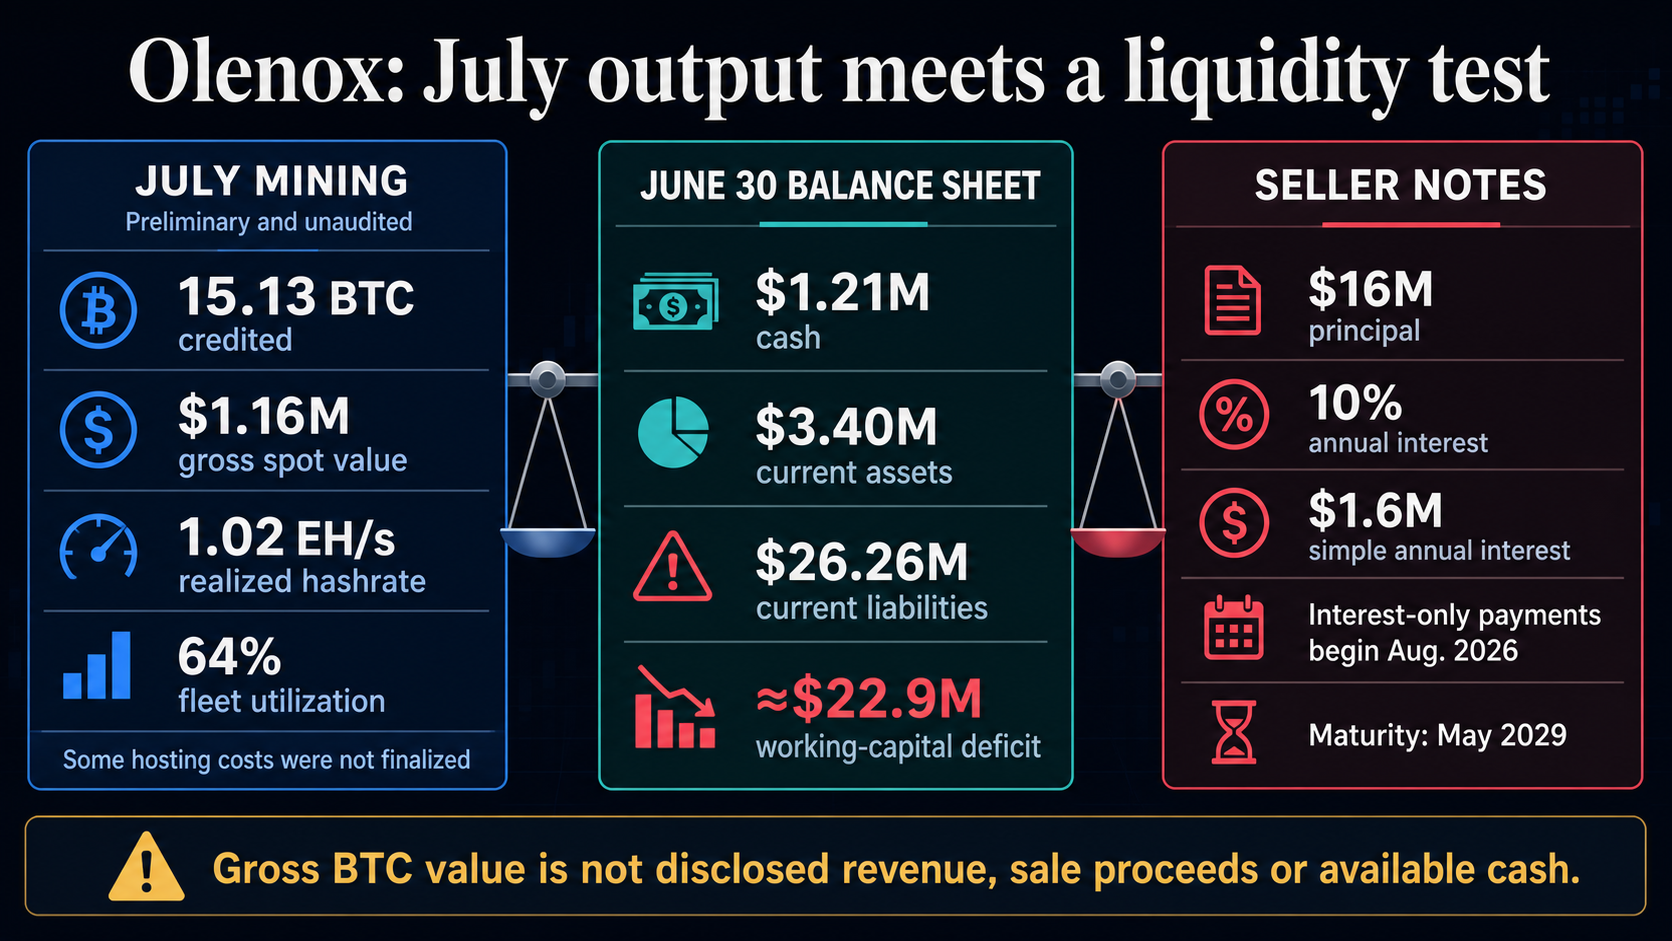
CS Digital generated $1.45 million of revenue and a $564,104 net loss from the May 26 acquisition through June 30. That period covers just over a month. The final July hosting bill remains the missing bridge between headline production and cash generation.
By contrast, July’s miners ran at third-party Texas facilities using grid power. Olenox’s plan is to convert its own natural gas into off-grid compute at a targeted cost below $0.02 per kilowatt-hour. That plan was not part of the month’s results.
Finally, Olenox also announced an Aug. 19 non-binding acquisition letter of intent. It carried an approximately $20 million stated price, primarily in preferred stock plus common stock and cash. The proposal extends its expansion ambitions. Even so, the immediate funding test rests on disclosed mining margins, seller-note payments and access to capital.

 cryptoslate.com