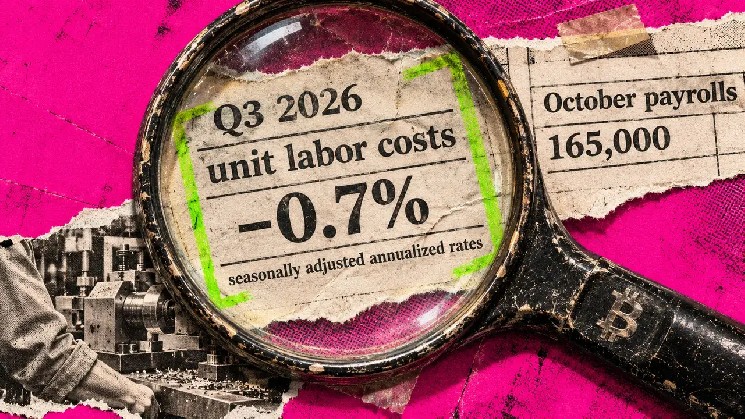
That complicates a reading of the November 6 employment report as an automatic inflation warning. October payrolls increased 165,000, above the prior 12 months' average monthly gain of 48,000. Average hourly earnings for private nonfarm employees rose 0.4% over the month and 3.1% over a year.
The reports cover different periods and measures. Third-quarter productivity does not establish how productive workers were in October, and its annualized growth rate cannot simply be subtracted from monthly earnings growth. Higher hiring and pay alone leave the question of labor costs per unit of output unanswered.
Lower labor costs leave the Fed with an inflation problem
Nonfarm business unit labor costs remained 2.4% higher than a year earlier. The quarterly decline eases one source of cost pressure, while leaving both the durability of that improvement and its effect on consumer prices unsettled.
The Fed's latest decision illustrates the policy tension. On October 28, before either November labor release, the Federal Open Market Committee held its target range at 3.75% to 4.00% in a 10-2 vote. Lisa Cook and Beth Hammack preferred a quarter-point increase.
That statement described productivity growth as strong while calling inflation elevated. The two conditions already coexisted in the Fed's assessment, limiting the case for treating better productivity as an automatic signal of easier policy.
For Bitcoin, the financing channel depends on what happens to rate expectations. Expected short-term rates can influence longer-term rates, borrowing terms and the relative attractiveness of assets. A sustained decline in inflation pressure could ease a potential rates headwind for Bitcoin if it brings lower expected rates and funding costs.
Persistent inflation or upward labor-cost revisions would weaken the case for relief in Bitcoin prices.

 cryptoslate.com