The longer-term futures chart offers additional perspective. Bitcoin futures open interest approached $90 billion during the previous market peak before contracting sharply as prices retreated. Current $BTC derivatives positioning around $54.78 billion remains substantially below those highs, even as recent sessions show renewed activity. That combination suggests speculative appetite has returned without approaching the extremes witnessed during the earlier rally.
Bitcoin Options Open Interest Favors Calls Over Puts
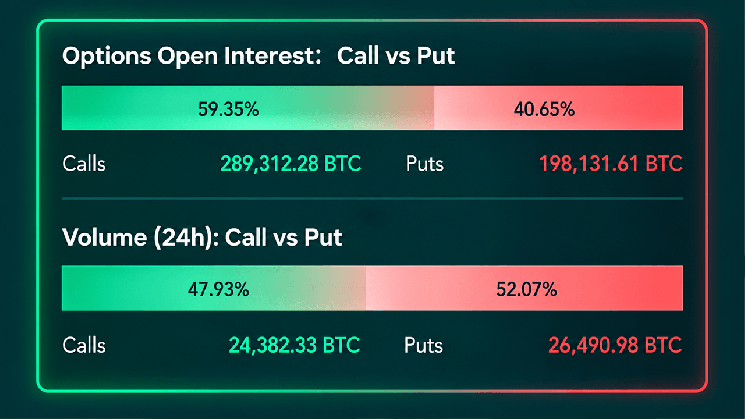
Bitcoin’s options market presents a distinctly bullish positioning profile. Coinglass reports 289,312.28 $BTC in outstanding call options against 198,131.61 $BTC in puts, giving calls 59.35% of total options open interest. Combined outstanding positions amount to approximately 487,443.89 $BTC. Calls generally benefit from rising prices, while puts provide downside exposure or protection, although individual strategies can complicate that straightforward interpretation.
Trading volume tells a slightly different story. Over the preceding 24 hours, puts accounted for 26,490.98 $BTC, or 52.07% of options volume, compared with 24,382.33 $BTC in calls, representing 47.93%. Crypto traders may be holding bullish positions while simultaneously purchasing downside protection. In other words, the options crowd appears optimistic about tomorrow, but isn’t leaving today’s umbrella at home.
Deribit’s largest listed positions concentrate around near-term upside strikes. Its Oct. 30 $95,000 call leads with 19,951 $BTC in open interest, followed by the $100,000 call with 11,284.3 $BTC and the $90,000 call with 10,710.6 $BTC. December contracts also feature prominently, including $80,000, $100,000, and $120,000 calls, alongside a $60,000 put. These concentrations reveal positioning preferences, not guaranteed price destinations.
CME Bitcoin Options Reveal Lower Exposure and Shorter Expirations
Cryptoquant’s CME options data reveals a substantial contraction in outstanding positions since late 2025, when put exposure frequently exceeded $200 million. By late October 2026, daily stacked positioning had dwindled to comparatively modest levels, with puts generally exceeding calls.
CME’s expiration breakdown also shows substantial exposure concentrated within one to two months, alongside smaller positions extending into subsequent quarters. The institutional options market appears considerably less crowded than during its previous peak.
Bitcoin Options Max Pain Levels Center on $81,000
With the Oct. 30 expiration approaching, max pain estimates cluster near bitcoin’s prevailing price. Deribit shows approximately $78,000 for Oct. 30, while Binance and OKX indicate roughly $81,000. December’s major expiration presents another wrinkle: Deribit’s max pain sits near $75,000, compared with approximately $81,000 on Binance and $78,000 on the trading platform OKX. Max pain represents the theoretical settlement price minimizing aggregate option-holder payouts, not a dependable price forecast.
Taken together, bitcoin’s derivatives markets reveal expanding futures exposure, call-heavy options positioning and renewed demand for downside hedges. The $90,000-to-$100,000 strike concentration highlights bullish ambitions, while exchange-specific max pain levels suggest a more complicated near-term contest.
Bitcoin may be sitting at $81,700 at the time of writing, but derivatives traders have already placed their bets across a considerably wider battlefield.

 news.bitcoin.com