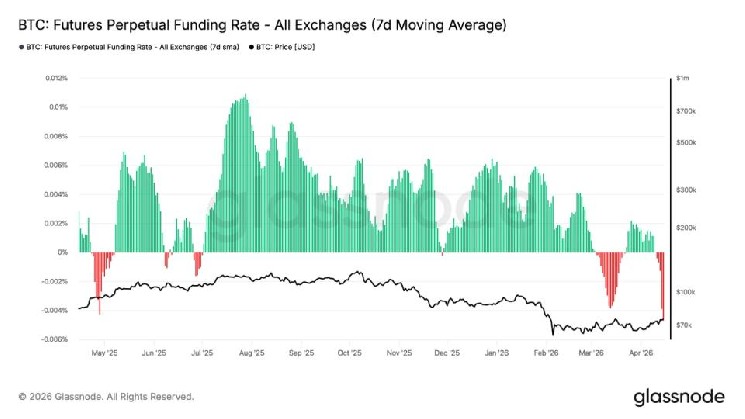
Despite the current sustained stretch of negative funding throughout March and April, bitcoin has continued to grind higher, climbing from the low to mid $60,000s to around $75,000.
Historically, deeply negative funding rates have often coincided with local bottoms in bitcoin’s price. This dynamic typically reflects crowded short positioning, which can create the conditions for a squeeze higher as bearish bets are unwound.
This pattern has played out across multiple market cycles. In March 2020, during the COVID-19 induced market crash, bitcoin fell to around $3,000 as funding rates turned sharply negative.
A similar setup emerged in mid 2021 amid China’s mining ban, when prices dropped to $30,000. Funding rates were also at their most extreme during the FTX collapse in November 2022, when bitcoin bottomed near $15,000.
The trend continued into 2023, when funding rates flipped negative during the Silicon Valley Bank crisis, coinciding with bitcoin briefly dipping below $20,000 before recovering. More recently, episodes such as the yen carry trade unwind in August 2024 and the April 2025 “Liberation Day” selloff also saw negative funding align with local lows.
The persistence of negative funding rates suggests that bearish positioning remains elevated, even as price action trends higher. This divergence may indicate that the market is climbing a wall of worry, with short positioning potentially acting as fuel for further upside.

 coindesk.com