coindesk.com
Pair traders hunting for an edge might want to focus on a little-known gauge tied to bitcoin $BTC$91,878.33 and the S&P 500.
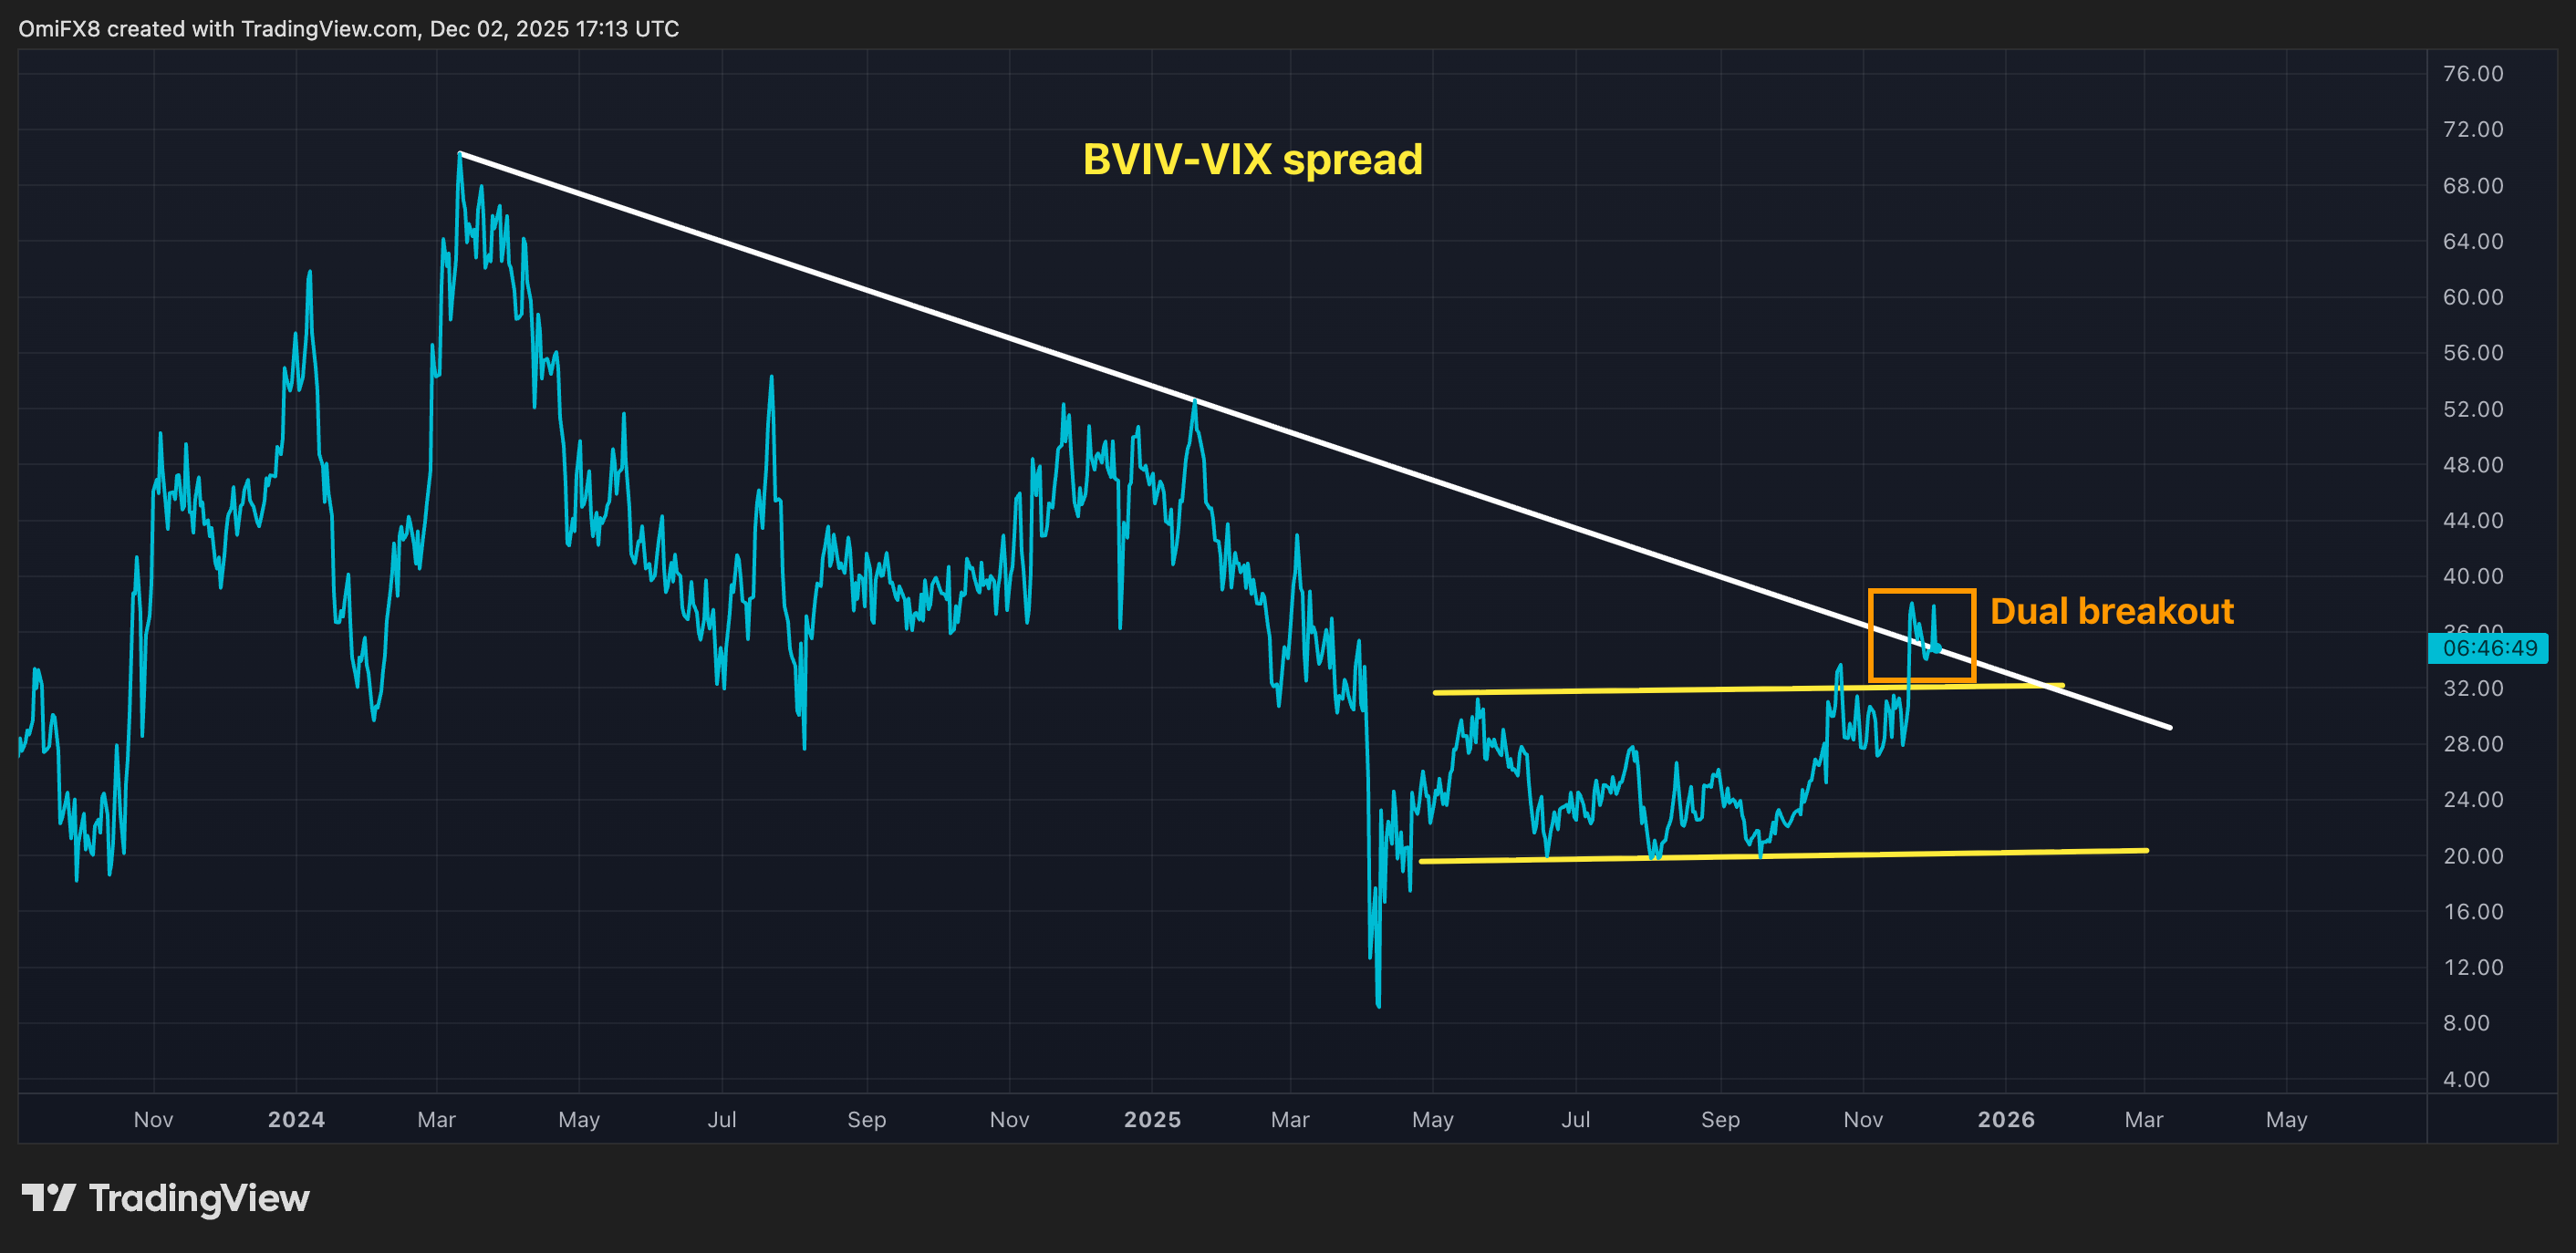
That gauge is the spread between Volmex’s BVIV – the 30-day implied volatility index for $BTC – and its S&P 500 counterpart, the VIX index. The spread has started to widen again, suggesting $BTC volatility is expected to outpace equity market risk.
Implied volatility is influenced by demand for options or hedging instruments.
"When the BVIV-VIX spread widens, it typically signals that markets expect higher volatility in crypto than in equities," Volmex's Founder Cole Kennelly told CoinDesk. "Crypto options markets adjust more rapidly to liquidity and macro catalysts, so implied volatility often moves ahead of traditional markets."