$SOL is trading near $63, and the disconnect between network momentum and token price can be explained by the fact that activity does not equal value capture, according to Jake Kennis, senior research analyst at Nansen.
Fees, stablecoin flows, tokenized equity volume, and ETF flows each benefit validators, issuers, platforms, and market makers before reaching $SOL holders. In Solana's current fee structure, the connection between network usage, token burn, and $SOL value capture is weaker than the headline activity numbers suggest.
The fee structure behind the gap
Solana's base fees are split 50% to burn and 50% to block producers. Priority fees, which dominate activity during high-throughput periods, flow 100% to validators after SIMD-0096.
That means a busy day on Solana with high-priority-fee activity and dense block usage routes the bulk of fee revenue to validators, with burn staying flat regardless of throughput.
SIMD-0547, currently under discussion, argues that Solana's burn rate is around 648 $SOL per day, even at sustained high throughput.
On a network processing billions in daily volume, that figure reflects a design flaw in which usage accrues to the network's operators and application layer before it accrues to $SOL as an asset.
Users can settle $16 billion in stablecoins across Solana while holding only the minimum $SOL required for transaction fees. Equity trading volume benefits the platforms and brokers facilitating those trades. App revenue accumulates at the protocol and frontend layer.
Kennis noted that the breakdown from the $76-$98 range toward the mid-$60s reflects macro risk-off pressure repricing a high-beta asset, with supply dynamics, holder distribution, and broader liquidity conditions governing $SOL's price in ways positive headlines cannot immediately reach.
The macro layer
Ryan Day, CMO of Solstice, said the SpaceX IPO is pricing this week, targeting a valuation of roughly $1.75 trillion and at least $75 billion in proceeds, with Reuters reporting that retail investors have been allocated up to 30% of the shares.
OpenAI and Anthropic are queued behind it, and when capital of that scale moves to market, risk assets across equities, credit, and crypto reprice to raise cash.
Every high-beta asset is absorbing the same pressure, and $SOL's drawdown is a position in that read, one shared with Bitcoin, which has been trading near $61,500.
Nasdaq's fast-entry rule could allow eligible newly listed mega-caps to enter the Nasdaq-100 within 15 trading days of listing, drawing passive fund demand into SpaceX after it begins trading. The mechanism extends the time speculative capital stays repositioned away from crypto.
Across a longer horizon, the sustained distance between $SOL's price and Solana's fundamental momentum points to the value-capture structure.
The bear case with substance
Day identifies the structural criticism of Solana's tokenomics, which run on an 8% initial inflation rate, a 15% annual disinflation rate, and a 1.5% long-term floor.
At the current pace of disinflation, the path to terminal inflation takes roughly 5.7 years. During that period, $SOL supply grows continuously, and without burn, staking demand, or other sinks offsetting issuance at scale, dilution becomes the dominant tokenomic force regardless of ecosystem activity.
Regarding the memecoin reputation due to Pump.fun, Day points out that every major chain chased the same memecoin trading cycle, and singling out Solana for a phenomenon that played out identically on Ethereum, Base, and BNB Chain reflects an insider framing error applied unevenly.
The inflation critique runs on specific numbers, while the memecoin critique is a reputational hangover applied to a trade every major chain ran.
What the community is voting on
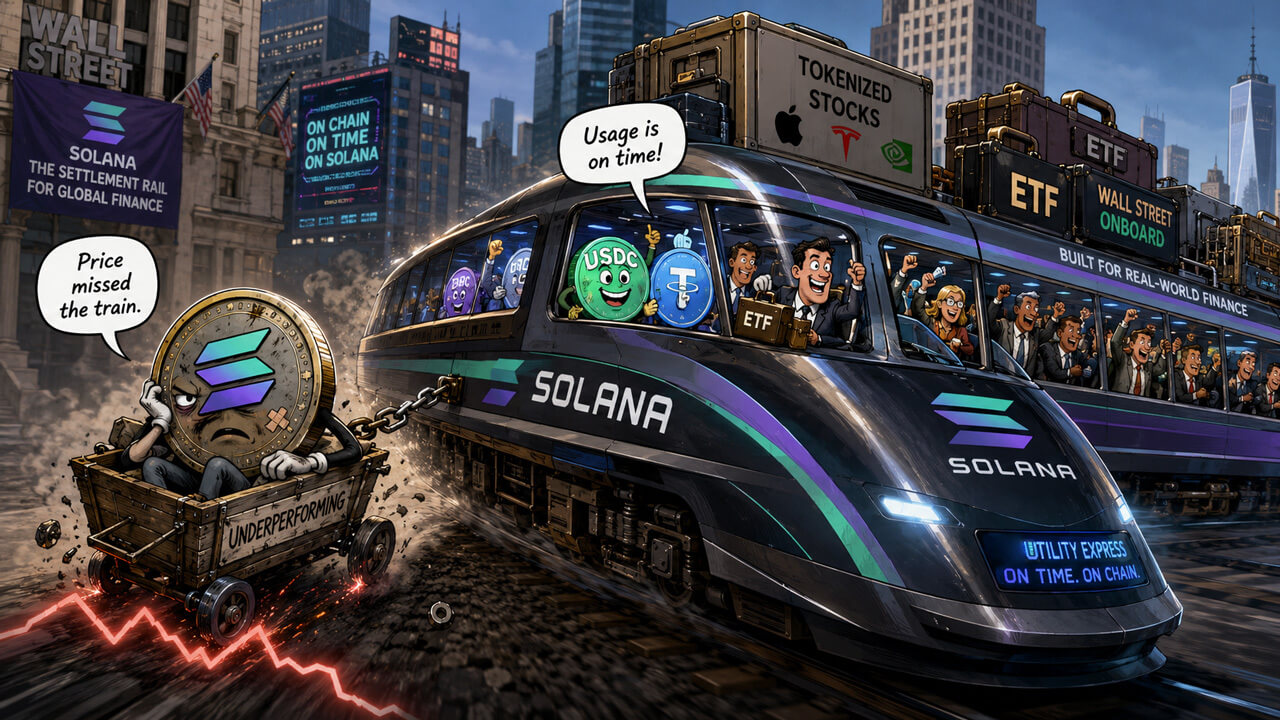
The reform proposals already in discussion are a direct response to the value-capture gap the market is pricing in.
SIMD-0550 proposes doubling Solana's annual disinflation rate from 15% to 30%, thereby compressing the path to a 1.5% terminal inflation rate from roughly 5.7 years to 2.8 years.
At current prices, the proposal's backers estimate the change would reduce future $SOL emissions by approximately $1.5 billion.
Anatoly Yakovenko has publicly backed the direction, and the vote on the strongest bear case in Solana tokenomics is happening in the open.
SIMD-0547 addresses Solana fee burn by adding a resource-based base fee that is fully burned, designed so burn scales directly with network resource consumption as priority fees route to validators.
If adopted, days with genuine network stress would generate burns in the tens of thousands of $SOL, closing the gap between network activity and direct token value capture that 648 $SOL per day leaves open.
Validator support, community coordination, and activation timelines introduce meaningful uncertainty. Solana's core community is openly debating both the supply and burn sides of the tokenomics equation, while the market is demanding answers on exactly those points.
If macro liquidity returns as the SpaceX IPO wave clears and SIMD-0550 and SIMD-0547 move toward activation, $SOL gains a credible path to re-rating via lower future dilution, higher burn per unit of activity, and an infrastructure already demonstrating ETF demand, institutional settlement rails, and tokenized-equity dominance.
The assets with documented real usage are historically the ones that reprice first when risk appetite recovers.
If reforms stall, inflation stays the dominant tokenomic force, and macro pressure persists, Solana's contradiction deepens.
The chain accumulates real activity through stablecoin settlement, equity trading, and institutional access, while $SOL captures a shrinking share of what that activity is worth.
Proving $SOL captures what the network is becoming is what the market is waiting for.

 cryptoslate.com